It's not how much you owe. It's what it costs to carry.
Six plain rules sit behind every loan we arrange, whether it's a first home, a family guarantee or a debt recycling structure your adviser has suggested. They shape what we recommend, when we tell you to wait or stay put, and how we look after you once the loan is settled. Rates and rules change. These don't.
It's not how much you owe. It's what it costs to carry. Now, and if things change.
Two households with the same debt can be in very different positions. What matters is what it costs each month to keep the loans and property going, measured against what you bring home, and whether you could still carry it if rates rose, an income dropped or the tenant left. We count your buffer in months of that cost, and we test the plan against a range of outcomes rather than a forecast.
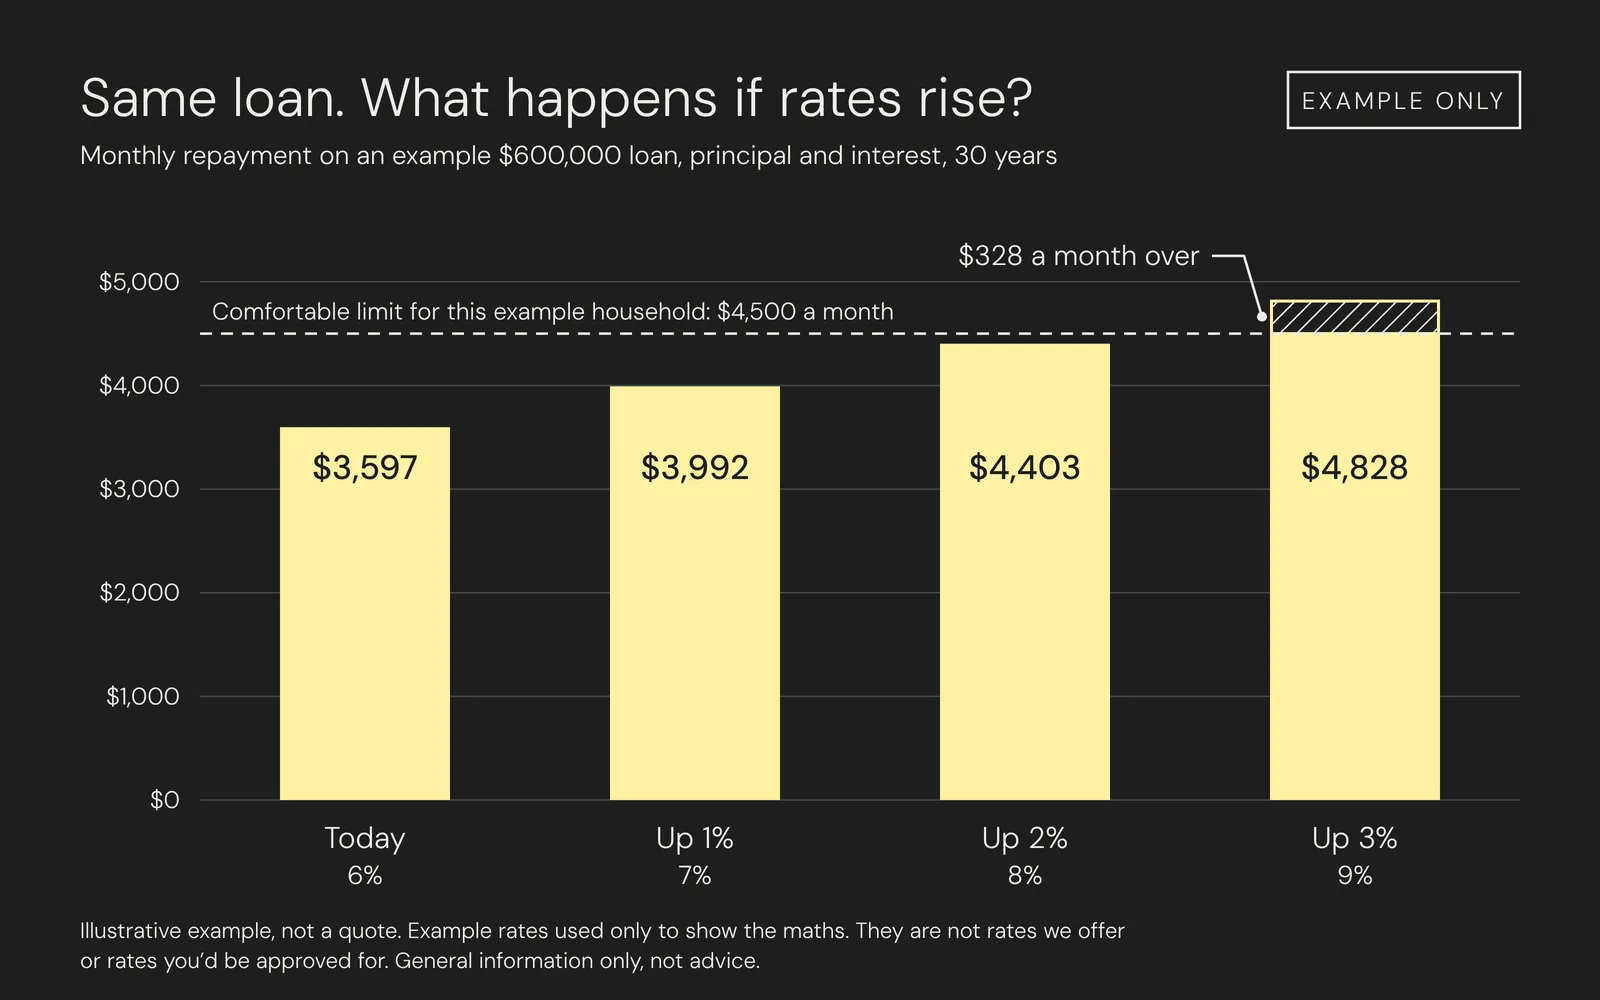
Illustrative example, not a quote. Example rates used only to show the maths. They are not rates we offer or rates you'd be approved for. General information only, not advice. Get the structure right, then chase the rate.
A sharp rate on the wrong structure can cost more over time than a fair rate on the right one. How the loan is split, where the offset sits and keeping purposes separate decide what you can do later, and how easy it is to change course.
Stay ahead of your loan, so you're always informed and in control.
The days of setting up a loan and forgetting about it are gone. Rates, rules and life all move, so we stay proactive and take that on as your broker. Every 6 months, we ask your lender to review your rate. At 12 and 24 months, you get your Loan Health Check, and you can ask for a Property Health Check any time. It isn't about refinancing for its own sake. It's about you having the full picture early enough to act, so the decisions stay yours.
Do our part well. Bring in the right expert for the rest.
We're experts in lending and loan structure. When a question is really tax, legal, financial advice or specialist lending, we say so. Then we introduce the right person, or work alongside your accountant, adviser, conveyancer or solicitor, so nothing falls through the gaps.
Technology does the busywork so we can do the people work, and your information is protected.
Good systems mean faster answers and fewer chased documents, so more of our time goes on you and your partners. We collect only what we need, keep it secure and share it only with your consent. Read our privacy policy
Straight answers, even when it's not what you want to hear.
We'll tell you what we actually think, even when that's “stay put” or “wait”. Most clients pay us nothing. We're usually paid by the lender. If a fee ever applies, we'll quote it upfront and you'll agree to it before we start. We're not the type of people who simply say no. If we get there, it's because of what our investigation found, and we'll walk you through it and show you the steps to have it re-assessed.
Want to talk it through?
Thirty minutes with Craig or Nick. Most clients pay us nothing.
Book a 30-minute callGeneral information only. It doesn't consider your objectives, financial situation or needs.